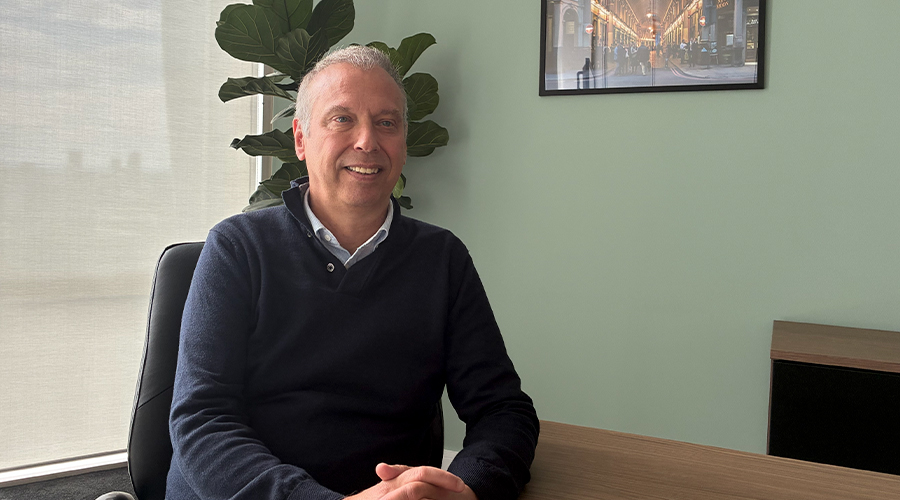
Following the recent arrival of Steven Geerlings to HCR Law’s Banking and Finance team, we spoke to him about his international career in asset-based lending, the challenges of cross-border finance and the developments shaping the lending market across Europe.
How has your career taken you across Europe?
Besides my time in private practice, working from London for more than 20 years in asset-based lending (ABL), I have worked in the Netherlands, both in-house and in private practice, in Belgium on banking regulations at the European Commission and in Germany managing a finance business for Deutsche Bank and GE Capital.
I started my career in academia as a financial regulation research fellow at the University of Bologna. During the first 10 years of my career, I worked predominantly in capital markets and structured finance. I moved into ABL when I helped establish the business for Deutsche Bank with expats from the US and Canada.
How did managing this business for Deutsche Bank shape your asset-based lending experience?
It was a steep learning curve. We funded channels for a diverse range of manufacturers, including Cisco, HP, Suzuki, Nissan, Kia, Sunseeker, Ferretti Yachts, Fairline Yachts, Bombardier and Piaggio scooters, but also caravans, furniture and even musical instruments. Credit lines for distributors and local dealers ranged from €500,000 to €325m.
We reached an annual funded transaction volume in Europe exceeding €20bn. We packaged receivables portfolios into securitisations, and we also offered off-balance-sheet financing. Many of our larger funding lines were participated with other lenders and much of our lending was floor-planning.
We operated in more than 27 jurisdictions. As you can imagine, before long most of my time was spent dealing with distressed situations, including insolvencies and fraud cases.
Why is experience in work-out situations so important in asset-based lending?
Several clients return to me for assistance when complex cross-border transactions that we have put together encounter difficulties over time. Fortunately, many situations can be resolved by scaling the exposure and enhancing operations.
When fraud is involved, we move into different territory, and the challenge becomes managing a work-out across different jurisdictions. That requires in-depth knowledge of local laws and practices, combined with a workable international strategy.
When putting the documentation for these transactions together, I usually arrange an exit strategy meeting for the lending client with local experts as early as possible. However, such a meeting can also be very helpful for borrowing clients.
What kind of hurdles do you typically encounter when working across several jurisdictions?
In a civil law situation, as opposed to common law, many challenges fall into similar categories. For receivables, we see tension between outright assignment, or ‘true sale’, and the creation of security interests. Here, we are dealing with the risk of recharacterisation, which can leave a lender unintentionally unsecured.
When taking security over inventory, we may need to consider dispossession requirements. In addition, we may face inoperable requirements for the perfection of assignment or security, such as the involvement of bailiffs or prohibitive administrative requirements for registering security or notifying debtors. As a comparison to common law, we are facing some similar considerations when putting together a fixed charge.
More generally, we must consider potential conflict of laws where assets are affected by the laws of several countries, for instance while in transit or where receivables involve creditors and debtors in various jurisdictions.
What is often overlooked when dealing with cross-border aspects in a transaction?
Just as in domestic transactions, it’s imperative that the legal documentation reflects the operational reality. And vice versa, operations must support the mandatory legal requirements.
Often, the international aspects of a transaction are approached from a theoretical perspective. That can leave unresolved uncertainties which may lead to the conclusion that funding in a specific jurisdiction presents an unacceptable risk.
In the UK, we have ended up with a lending market that can be heavily focused on foreign legal considerations, sometimes disconnected from local day-to-day operations and practical realities. As a result, many opportunities are, in my view, misjudged.
We should remember that local ABL business in countries such as Italy, France and Spain is being conducted successfully and is often thriving and profitable for local lenders that are likely to be as risk-averse as lenders in the UK.
To achieve a proper risk assessment, it can be useful to review local enforcement practices with local experts in order to identify appropriate operations and legal requirements tailored to the operations of the lender in the UK. The cost is often justified for transactions involving multiple assets: not only receivables, but also inventory, plants and machinery, real estate, intellectual property rights and shares, as well as multiple entities in various jurisdictions.
For transactions in the UK involving only receivables with debtors in various countries, legal counsel with operational experience, supported by local counsel with practical experience, can be sufficient for addressing the relevant risks.
How are local laws across Europe evolving to support cross-border asset-based lending?
As competition between international lenders for cross-border deals in the European market has increased, legislators have been under pressure to facilitate transactions within their local jurisdictions.
For instance, in several European countries, we have seen the removal of the notification to debtors as a perfection requirement for the assignment of receivables. In these jurisdictions, a duly signed and dated assignment agreement constitutes perfected assignment for assignee and assignor, and for an insolvency administrator.
In France, the involvement of a bailiff for the notification to debtors in an assignment of receivables (cession des creances) has been replaced by a certain date requirement, which effectively requires a confirmation of receipt by the debtor. French case law will determine whether this can include an implied confirmation.
Furthermore, international institutions such as UNCITRAL, UNIDROIT and the EU have taken initiatives to reduce administrative and regulatory burdens on the operation of finance transactions and to harmonise regulations, particularly in relation to insolvency. I was involved in the creation of a Model Law on Factoring by UNIDROIT in 2025 as an industry representative.
How do borrowers benefit from your cross-border expertise?
For borrowers, it’s important to understand the lenders’ operational requirements to mitigate the risks associated with lending against foreign assets. We advise borrowers on those requirements and, where necessary, on adjusting operations to prepare their business for cross-border ABL.
We can also review the corporate structure of a borrower’s group of companies to assess whether subsidiaries in certain jurisdictions can be used for dual assignment structures or other arrangements that facilitate funding.
Such adjustments may have tax or commercial consequences for the borrower, and our role is to help ensure these are kept to a minimum while still meeting lenders’ requirements.
How can we help you?
Related articles
News
23 June 2026
3 minute read
Asset-based lending expert joins HCR Law’s Banking and Finance team
Read more
Article
18 February 2026
8 minute read
From slowdown to rebound: UK mid‑market acquisition finance shows signs of revival
Read more
Article
18 February 2026
8 minute read
Real estate finance in 2026: cautious confidence for commercial and development lending
Read more